
pawnbroking guide
Borrowing Against an Audemars Piguet Royal Oak
What lenders look for when valuing an Audemars Piguet Royal Oak as security, from reference and dial to bracelet wear and the risks of over-polishing.
The steel watch that changed the rules
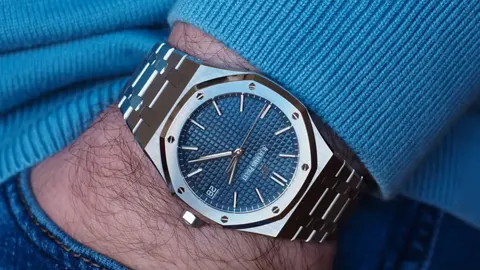
When Audemars Piguet unveiled the Royal Oak in 1972, it was a provocation. Designed by Gérald Genta, it was a luxury watch made of steel, priced like a precious-metal piece, with an octagonal bezel secured by eight visible hexagonal screws and a bracelet that flowed seamlessly from the case. Many in the industry doubted it would sell. Over time, it became one of the most influential designs in modern watchmaking and helped create the category of the luxury sports watch that dominates collector attention today.
That history matters to lenders because it underpins the Royal Oak’s standing in the secondary market. The model is instantly recognisable, widely collected and traded internationally, which makes it attractive collateral. Yet it also has particular vulnerabilities that a careful lender will examine closely, from the delicacy of its finishing to the importance of specific references. Knowing what a pawnbroker is looking for can help owners understand the offer they receive and avoid mistakes that quietly reduce value.
Knowing exactly which Royal Oak it is
The Royal Oak family is broad. It includes the slim, time-only models descended from the original design, often nicknamed ‘Jumbo’, larger self-winding versions with date, chronographs, the more muscular Royal Oak Offshore introduced in the 1990s, and a range of complications and gem-set pieces. Case sizes, metals and dial colours vary widely. Each of these variations has its own market, and a lender will first establish the precise reference, since demand can differ markedly even between watches that look alike to a casual observer.
Steel and certain two-tone or precious-metal time-only references tend to attract particularly strong interest, while some gem-set and less common variants have a narrower audience. Discontinued references may be sought after or simply superseded, depending on collector sentiment. Lenders consult recent sales data and their own experience to judge where a given watch sits. As with any fashionable model, they will also consider how far current prices reflect a durable level of demand rather than a temporary peak in the market.
Finishing: the Royal Oak’s beauty and weakness
Much of the Royal Oak’s appeal lies in its finishing. The case and bracelet alternate between satin-brushed surfaces and narrow polished bevels, with crisp, precise edges catching the light. Achieving this by hand takes considerable skill, and collectors examine it closely. Unfortunately, those same surfaces show wear readily, and the sharp transitions are easily softened by careless polishing. Once the bevels have been rounded or the brushed lines blurred, the watch loses a significant part of its character.
For this reason, lenders scrutinise the case and bracelet under good light and magnification. A Royal Oak with honest wear but intact edges is generally preferable to one that has been polished to a high shine by an inexperienced hand. The manufacturer can refinish cases during a service, restoring the intended finishing, and lenders will take such work into account where it is documented. Owners tempted to tidy up their watch before a valuation are usually better advised to leave it exactly as it is.
Dial, bracelet and movement checks
The Royal Oak’s dial is typically decorated with a ‘Tapisserie’ pattern, a grid of small raised squares whose precise scale and finish vary between references. Lenders inspect the pattern, printing, applied markers and hands under a loupe, since dial details are a common area where counterfeits and replacement parts reveal themselves. The integrated bracelet is examined for stretch, missing links and damage to the clasp. Because the bracelet is integral to the design, a replacement or badly worn example can have a notable effect on value.
The movement is also assessed, either through a display caseback or by opening the watch. The lender will want to confirm that the calibre is correct for the reference and that it runs within reasonable tolerances on a timing machine. Any sign of moisture, poor servicing or non-original parts will be noted. Water resistance, often taken for granted in a sports watch, depends on intact gaskets, so evidence of neglected servicing can influence the lender’s view of what the watch may need before resale.
Papers, provenance and routine checks
As with other sought-after modern sports watches, documentation carries weight with the Royal Oak. The warranty certificate, original box, purchase receipt and any service records from the manufacture help confirm authenticity, date and history. Extra bracelet links are worth bringing too, since a buyer with a larger wrist will need them. A watch without papers can still be accepted by a specialist lender, but the offer is likely to reflect the additional uncertainty and the smaller pool of buyers willing to purchase without documentation.
Lenders will also carry out identity and anti-money laundering checks, which are standard for high-value transactions, and search stolen-property databases using the watch’s serial number. Popular models attract thieves as well as collectors, so these steps are part of responsible lending rather than any reflection on the borrower. Arriving prepared, with identification, proof of address and whatever documentation exists, typically makes the valuation smoother and quicker for everyone involved, and leaves more time to discuss the offer itself.
Taking the loan with eyes open
A Royal Oak can support a meaningful loan, but the offer will always be a proportion of its realistic resale value rather than the highest price seen online. The lender needs a margin to absorb market movement, selling costs and the possibility that the watch is not redeemed. Understanding that logic makes it easier to judge whether an offer is fair, and comparing more than one specialist lender can help, particularly as knowledge of Royal Oak references varies from firm to firm.
Before signing, read the agreement in full. Check the interest rate, any charges, the length of the term and what happens if you wish to extend. Under UK consumer credit rules, you have at least six months to redeem and can repay at any time before the watch is sold. Ask how the watch will be stored and insured while pledged. A clear plan for repayment is the best way to ensure that a much-loved Royal Oak comes home again.